Learning What Money Reveals About How We Participate In Life
Money is one of those subjects that can become emotional very quickly. For some people, it represents security. For others, freedom. Status. Power. Opportunity. Survival. Success. Independence. Responsibility. Fear. For most of us, it probably represents several of those things at different times. But underneath everything we attach to money, it serves a much simpler function: Money is a resource.
It gives us access to things. It allows exchange. It provides options. It can increase our ability to respond to circumstances, pursue opportunities, help other people, build something, or prepare for an uncertain future. And because our financial resources are limited, money also requires us to make choices. That is where finances become particularly interesting from the perspective of personal development. Because how we manage our resources can reveal quite a bit about how we manage ourselves.
Money Makes Priorities Concrete
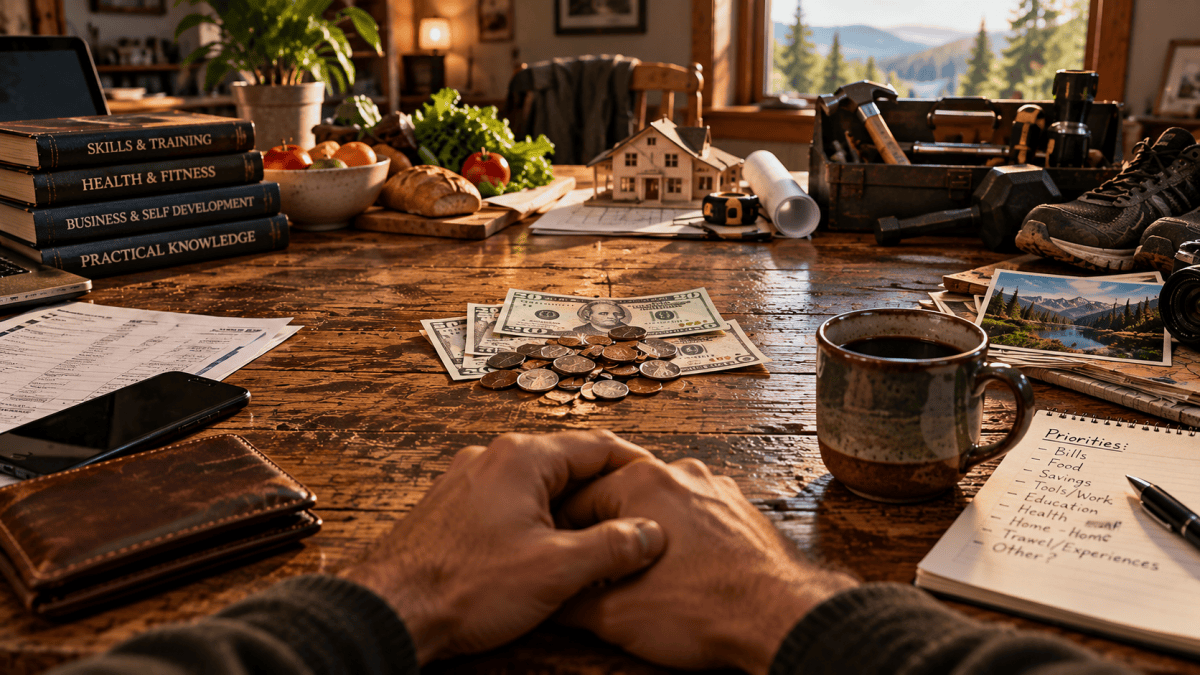
We can say that something matters to us. Money occasionally asks us to demonstrate it. That doesn’t mean everything important has a price. Many of the most important things in life don’t. But when we have limited resources and multiple things competing for them, we have to prioritize. Do we spend now or save for later? Do we purchase something we want or put that money toward something we need? Do we invest in education? Our health? A business? An experience? Our family? Our future? There isn’t one universally correct answer to those questions. Different people have different circumstances, responsibilities, goals, and values.
What matters developmentally is that we begin seeing our financial decisions as decisions. Sometimes we’re making them deliberately. Sometimes we’re making them emotionally. Sometimes habit is making them for us. And sometimes we’re spending money according to values we inherited from somebody else without ever deciding whether those values are actually ours.
Money Can Reveal Our Attachments
Finances are particularly good at exposing attachment because money becomes connected to so many other things. Status is an obvious example. We can purchase things because they’re useful, beautiful, enjoyable, or meaningful to us. We can also purchase them because of what we hope they communicate about us. Those aren’t necessarily the same motivation. Social comparison can become expensive. So can insecurity. So can boredom. So can impulsiveness. So can the need to prove something. At the opposite extreme, fear can cause us to become so attached to keeping resources that we become unable to use them even when using them would meaningfully improve our lives.
Neither spending nor saving is automatically healthy simply because we’re doing one rather than the other. The useful question is: What is driving the behavior? Money doesn’t create every issue it reveals. Sometimes it simply gives the issue somewhere measurable to appear.
Control What Is Actually Yours
Financial advice can sometimes become unrealistic because it treats every financial condition as though it were entirely the result of individual behavior. It isn’t. We participate in economic systems we don’t individually control. We don’t personally determine inflation. Housing prices. Interest rates. Taxation. Job markets. Wages across an industry. Economic recessions. Medical emergencies. Unexpected repairs. Or the economic circumstances into which we were born.
Pretending those things don’t matter isn’t personal responsibility. It’s simply inaccurate. But the opposite extreme isn’t particularly useful either. The fact that we cannot control the entire economic environment does not mean we have no influence over our financial position.
There are still questions that belong to us. What am I earning? What am I spending? What am I saving? What am I borrowing? What am I committing myself to financially? What skills could increase my options? What risks am I taking? What risks am I avoiding? What can I reasonably change? What can’t I change right now? This distinction between control and influence matters far beyond finances. We don’t need complete control over a situation before our choices matter within it.
Resources Create Options
One reason I prefer thinking about money as a resource is that it moves the conversation away from treating wealth as a measurement of human value. Having more money does not make someone a better human being. Having less doesn’t make someone inferior. But resources do matter.
A person with financial reserves has options that someone living from one emergency to another may not have. They may be able to leave a bad situation sooner. Take time to recover. Move somewhere else. Pursue education. Start a business. Repair something before it completely fails. Help someone. Absorb an unexpected expense. Or simply take enough pressure off themselves to think beyond the next immediate problem. That’s significant.
Money cannot solve every problem there is. But neither does pretending money doesn’t matter make financial pressure disappear. The objective doesn’t have to be endless accumulation. It can simply be developing enough command of our resources that our financial condition supports our lives instead of unnecessarily controlling them.
Sometimes The Investment Is In Ourselves
Not every valuable financial decision produces immediate financial returns. Education is a good example. We may spend money learning something because it increases our capabilities. Physical health is another. Equipment. Training. Professional credentials. Tools. Technology. A business. Sometimes the resource we’re purchasing gives us the ability to create additional resources later.
That doesn’t mean every expense we call an “investment” actually is one. That’s another place honesty becomes useful. If we want something because we want it, we can simply acknowledge that. We don’t have to manufacture an elaborate explanation about why every purchase is secretly an investment in ourselves.
But we can learn to distinguish between consumption and investment. Sometimes we’re buying an experience. Sometimes convenience. Sometimes entertainment. Sometimes capability. Sometimes a future opportunity. Understanding the difference helps us make the decision consciously.
Enough Is A Question Worth Asking
There is another financial question that receives less attention: How much is enough? If we never answer that, financial development can become an endless race. More income. More possessions. More security. More status. More accumulation. Then the goal moves every time we approach it. That doesn’t mean ambition is wrong. Wanting financial success isn’t inherently shallow. Wanting comfort isn’t a moral failure. Neither is wanting to build something substantial, leave something behind, or enjoy what we’ve earned. But it helps to know what we’re pursuing and why.
If money is supposed to create freedom, but acquiring it consumes every available part of our lives, eventually we should probably ask what kind of freedom we’re purchasing. If we’re sacrificing relationships, health, integrity, or everything we enjoy for financial success, we should at least consciously recognize the exchange we’re making. Maybe we still decide it’s worth it. But then it’s a choice rather than an unconscious transaction.
Financial Independence Begins With Participation
Independence doesn’t necessarily mean possessing enough money that we never need another person again. Human beings live through systems of exchange and interdependence. What financial independence can mean is becoming increasingly capable of participating in those systems without being unnecessarily controlled by our own unmanaged behavior.
Understanding what comes in. Understanding what goes out. Knowing what we’ve committed ourselves to. Preparing where we can. Developing capabilities that increase our options. Learning the difference between what we want and what we need without pretending we’re never allowed to want anything. And becoming increasingly deliberate about where our resources go. That won’t eliminate uncertainty. There will always be circumstances we cannot predict or control. But it can increase our ability to respond when those circumstances arrive.
Money Reflects Participation
Finances aren’t separate from personal development simply because money exists outside of us. Quite the opposite. Money sits at an interesting intersection between our internal world and external reality. Our values influence how we use it. Our emotions influence how we use it. Our habits influence how we use it. Our relationships influence it. Our careers influence it. Society influences it. And then our financial condition influences all of those things in return.
That makes money useful as more than something we earn and spend. It gives us another place to observe ourselves. We can ask: What does the way I manage my resources tell me about how I participate in my life? Not so we can judge every purchase. Not so we can reduce success to a bank balance. And not so we can pretend every financial difficulty is something we created ourselves. But so we can recognize the part that actually belongs to us. Because money is a resource. And resources create possibilities. The more consciously we manage the resources available to us, the more deliberately we can decide which possibilities we want those resources to help us create.

